
Short answer: Yes, for many veterans and active-duty service members, this market works in their favor. VA loans can mean no down payment and no monthly mortgage insurance, and with more homes for sale and less competition in many areas, VA buyers have more room to negotiate than they did a few years ago.
Today is Veterans Day, and it is a good moment to say this plainly: if you have served and you have been thinking about buying a home in Morris County or anywhere in North Jersey, your position may be stronger than you assume. The VA loan was always a valuable benefit. What has changed is the market around it.
We also hear a lot of outdated ideas about VA loans being slow, fragile, or unpopular with sellers. Most of that does not hold up when you look at the data.
What a VA Home Loan Offers Buyers in Morris County, NJ
Close to 4 million veterans and service members currently have an active VA home loan, and the Department of Veterans Affairs reports that over 343,000 homes were bought with VA benefits in its latest reported fiscal year.
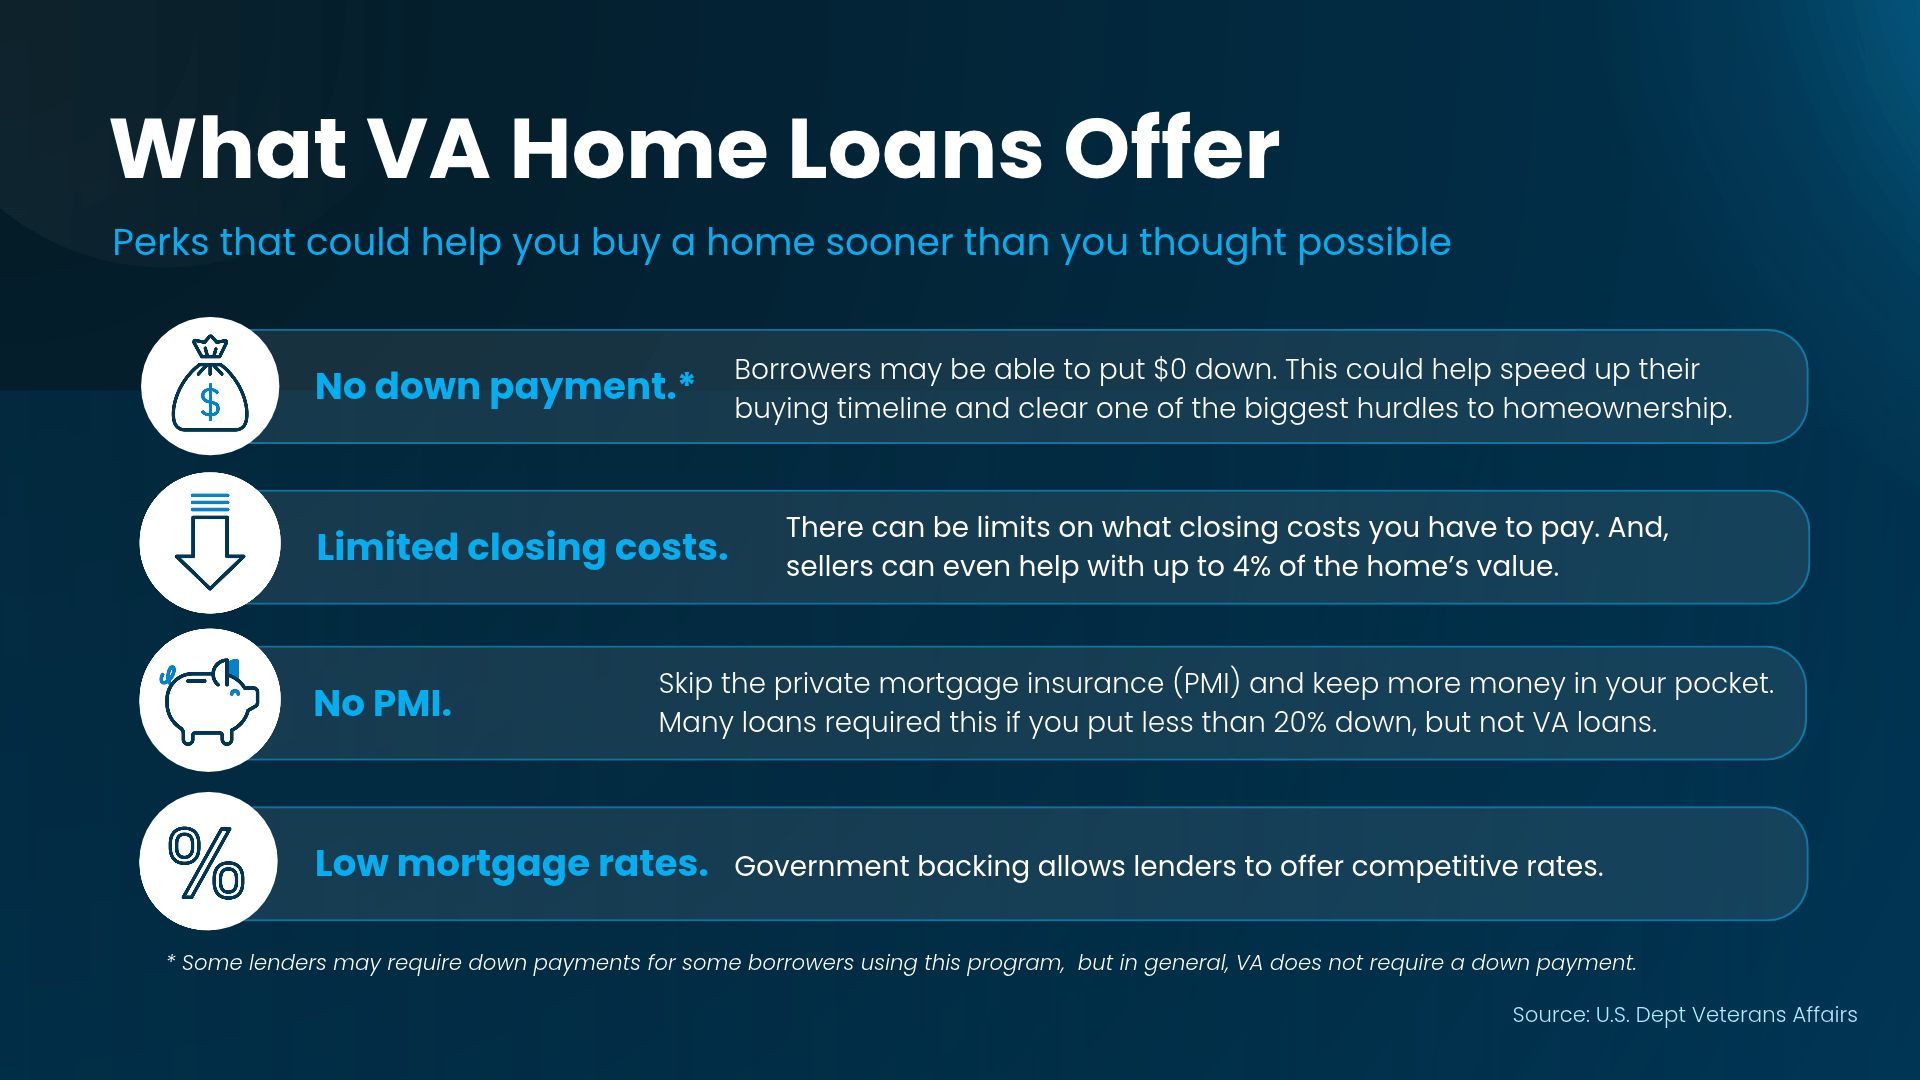
For buyers who qualify, the main advantages are simple:
- No down payment for many eligible borrowers.
- No monthly mortgage insurance, even when you put nothing down.
- Competitive interest rates, which can help keep the monthly payment lower.
Those benefits help in any market, and they carry extra weight right now. That helps explain why VA loan use has increased two years in a row.
Why VA Buyers Struggled a Few Years Ago
During the bidding-war years, VA buyers often had a harder time. When a listing drew a pile of offers, some sellers simply passed over VA financing.
A 2021 National Association of Realtors (NAR) survey showed how lopsided it was: 89% of sellers said they were likely to accept an offer backed by a conventional loan, but only 30% said the same about an offer using an FHA or VA loan.
Sellers worried that a VA loan would close more slowly, be harder to get across the finish line, or leave them paying for extra costs and repairs. Those worries did not match how VA loans actually perform.
VA Loan Myths vs. the Facts
A white paper from Vetted VA, built on 2025 mortgage data, looked at the most common concerns. Here is what it found:
- Myth: VA loans are denied more often. In fact, VA loans had the lowest denial rate of the group. About 8.2% of VA purchase applications were denied, versus 15.0% for conventional, 12.8% for FHA, and 12.5% for USDA loans.
- Myth: VA financing is less dependable. Of VA applications that reached underwriting, 90% went on to close. For conventional loans, that figure was 81%.
- Myth: VA appraisals drag on. A VA appraisal usually takes about 7 to 10 business days, roughly in line with conventional and FHA appraisals.
- Myth: The seller has to cover all of a VA buyer’s closing costs. VA buyers can pay many standard closing costs on their own, and the buyer and seller can negotiate which eligible costs the seller picks up.
More Negotiating Room for VA Buyers in North Jersey
With more listings and fewer competing buyers in many areas, sellers tend to be more flexible about financing than they were a few years back. That flexibility can go beyond getting your offer accepted.
Depending on the home and the town, you may be able to negotiate on price, ask for repairs, or request help with closing costs. Under VA guidelines, a seller can pay the buyer’s normal closing costs and also contribute concessions of up to 4% of the home’s value.
Put those pieces together and the picture is strong: no down payment, no mortgage insurance, and possible seller help with other costs. For a lot of buyers, that means keeping thousands of dollars in savings instead of spending it all at the closing table, which gives you some cushion after you move in.
What This Means in Morris County
Locally, the market has loosened up, though well-priced homes still move. Here is where things stand:
| Morris County single-family (Sept. 2026) | Sept. 2026 | Sept. 2025 |
|---|---|---|
| Homes for sale (inventory) | 757 | 663 (+14.2%) |
| Months supply of inventory | 2.5 | 2.2 |
| Median sales price | $737,500 | $722,500 (+2.1%) |
| Percent of list price received | 104.0% | 103.6% |
More inventory gives VA buyers more choices and more homes where negotiation is realistic, especially listings that have been sitting. At the same time, homes in Morris County are still selling above list on average, so on the most popular properties a clean, well-prepared VA offer still matters. Rates are part of the picture too: Freddie Mac’s 30-year fixed average was 7.18% for the week of November 5, 2026, which makes the VA program’s competitive rates and lack of mortgage insurance even more useful. If you are new to the process, our guide to first-time home buyer programs in New Jersey and our November 2026 Morris County market update are good next reads. You can also see how our team works with veterans buying or selling in New Jersey.
VA Home Loan FAQs for Morris County Buyers
Do I need a down payment to buy a home in NJ with a VA loan?
Many eligible veterans and service members can buy with no down payment through the VA program. Some lenders set their own requirements, so confirm with a VA-approved lender first.
Can a seller pay closing costs on a VA loan?
Yes. VA guidelines let a seller pay the buyer’s normal closing costs and also offer concessions of up to 4% of the home’s value. How much a seller agrees to cover is part of the negotiation.
Are VA loans harder to close than conventional loans?
The data says no. A 2025-data white paper from Vetted VA found VA loans had the lowest denial rate, and 90% of VA applications that reached underwriting closed, compared with 81% for conventional loans.
Bottom Line
If you are on active duty, have served, or know someone who has, it is worth talking with a local agent and a trusted VA-approved lender to find out what you qualify for. The VA benefit paired with today’s market could be a strong combination.
This article is general information, not legal, tax, investment or financial advice. Eligibility, loan terms and market conditions vary, and forecasts can change.
Sources
- U.S. Department of Veterans Affairs (VA home loan program data)
- National Association of Realtors (NAR), 2021 seller survey
- Vetted VA white paper based on 2025 mortgage data
- New Jersey REALTORS / ShowingTime, Morris County Local Market Update, September 2026
- Freddie Mac Primary Mortgage Market Survey, November 5, 2026
Adapted from Keeping Current Matters research.
Talk to the MorrisAgent Team
Want to see what this means for you? We’ll sit down and run the real numbers. Call (973) 200-4800, email [email protected], or stop by our office at 518 Main Street, Suite 102, Boonton. No pressure, and no surprises.