
Short answer: For many buyers, yes. Homes that need work typically sell for 20% to 30% below their market value, according to AmeriSave. In Morris County, where the October single-family median reached $773,000, that discount can be significant. The key is to budget for repairs and choose the right renovation loan before you make an offer.
If every move-in-ready home you like comes in above your budget, it may be worth a second look at the listings most buyers scroll past. A house that needs updating isn’t for everyone. Some people want to unpack and be done. But a home with a dated kitchen, worn floors or an older roof can lower the price of getting in quite a bit.
More buyers are noticing. Danielle Hale, chief economist at Realtor.com, has pointed out that with affordability still tight, fixer-uppers give people a way into the market along with the chance to shape a house into something that fits them. Here’s how our team thinks about it with buyers across Morris County.
Fixer-Upper Prices: How Much Could You Save?
A home that needs work usually carries a lower list price, because the next owner takes on the cost and effort of the repairs. AmeriSave estimates fixer-uppers typically sell for 20% to 30% under what they’re worth on the market.
To show what that can mean, Keeping Current Matters took the national median home price from the National Association of Realtors (NAR), $417,500, and applied a 25% discount, the midpoint of that range. That lands at $313,125, a gap of more than $100,000. It’s an illustration, not the typical price of a fixer-upper, but it shows how large the savings can be (see graph below):
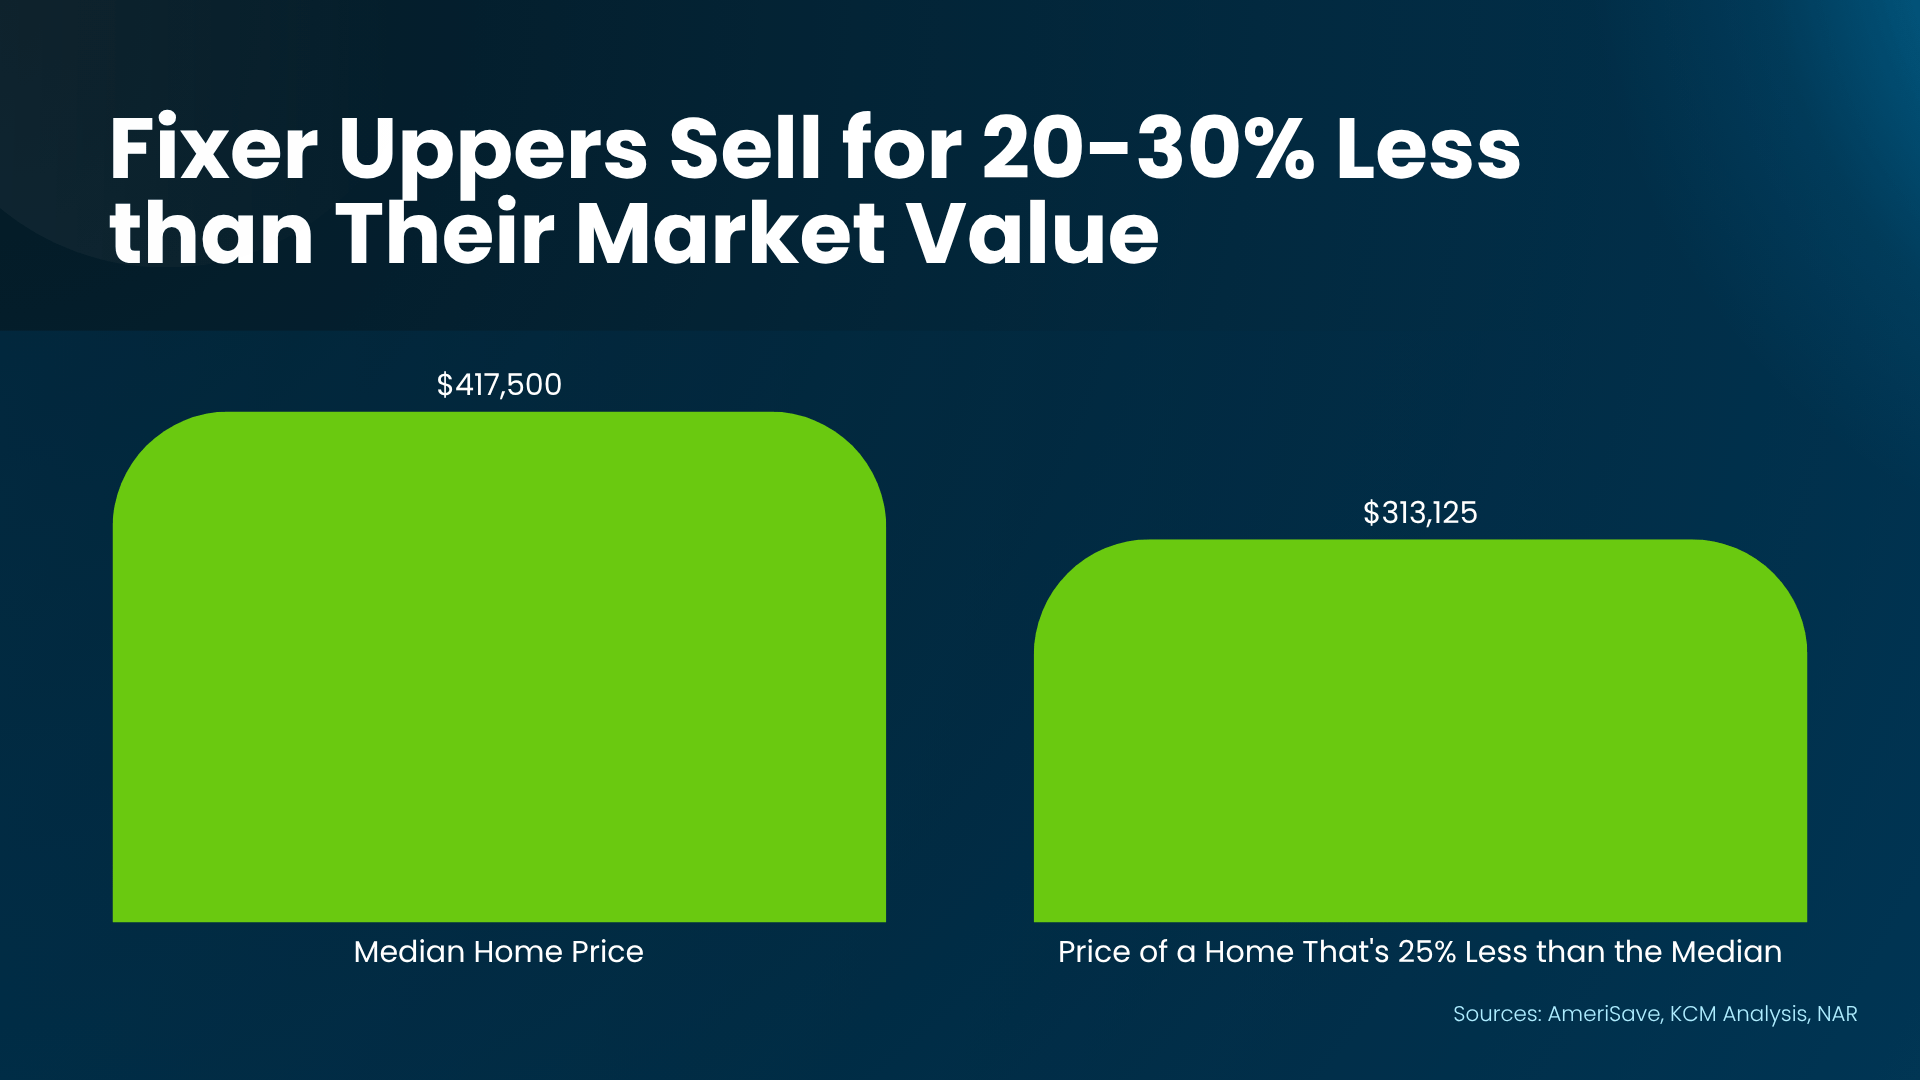
That difference up front can be what makes buying possible now instead of later. And most projects don’t have to happen in the first month. Many owners work through repairs in stages, as their budget allows.
The catch is that renovation costs climb quickly and can eat into those savings without a plan. Before you make an offer, have a contractor walk the house and price the work, then set a repair budget you’re comfortable with. A thorough home inspection matters even more on an older or neglected house. It’s also smart to check with the town for open or expired permits on past work; we cover that in our guide to open permits in NJ.
What This Means in Morris County, NJ
Local prices sit well above the national median, so the same percentage discount covers more ground here. This is where the Morris County single-family market stood in October 2026, according to NJ REALTORS:
| Morris County single-family (Oct. 2026) | Figure |
|---|---|
| Median sales price | $773,000 (up 3.8% from Oct. 2025) |
| Homes for sale | 704 (up 18.7% from a year earlier) |
| Days on market until sale | 31 |
| Percent of list price received | 102.9% |
Applying the same 25% example to our $773,000 median works out to about $193,000 below that figure. That’s simple math, not a promise; the actual discount depends on the home’s condition and the town. With more homes for sale than a year ago, buyers have more listings to choose from, including ones that need some work.
Renovation Loans: Finance the Home and the Repairs Together
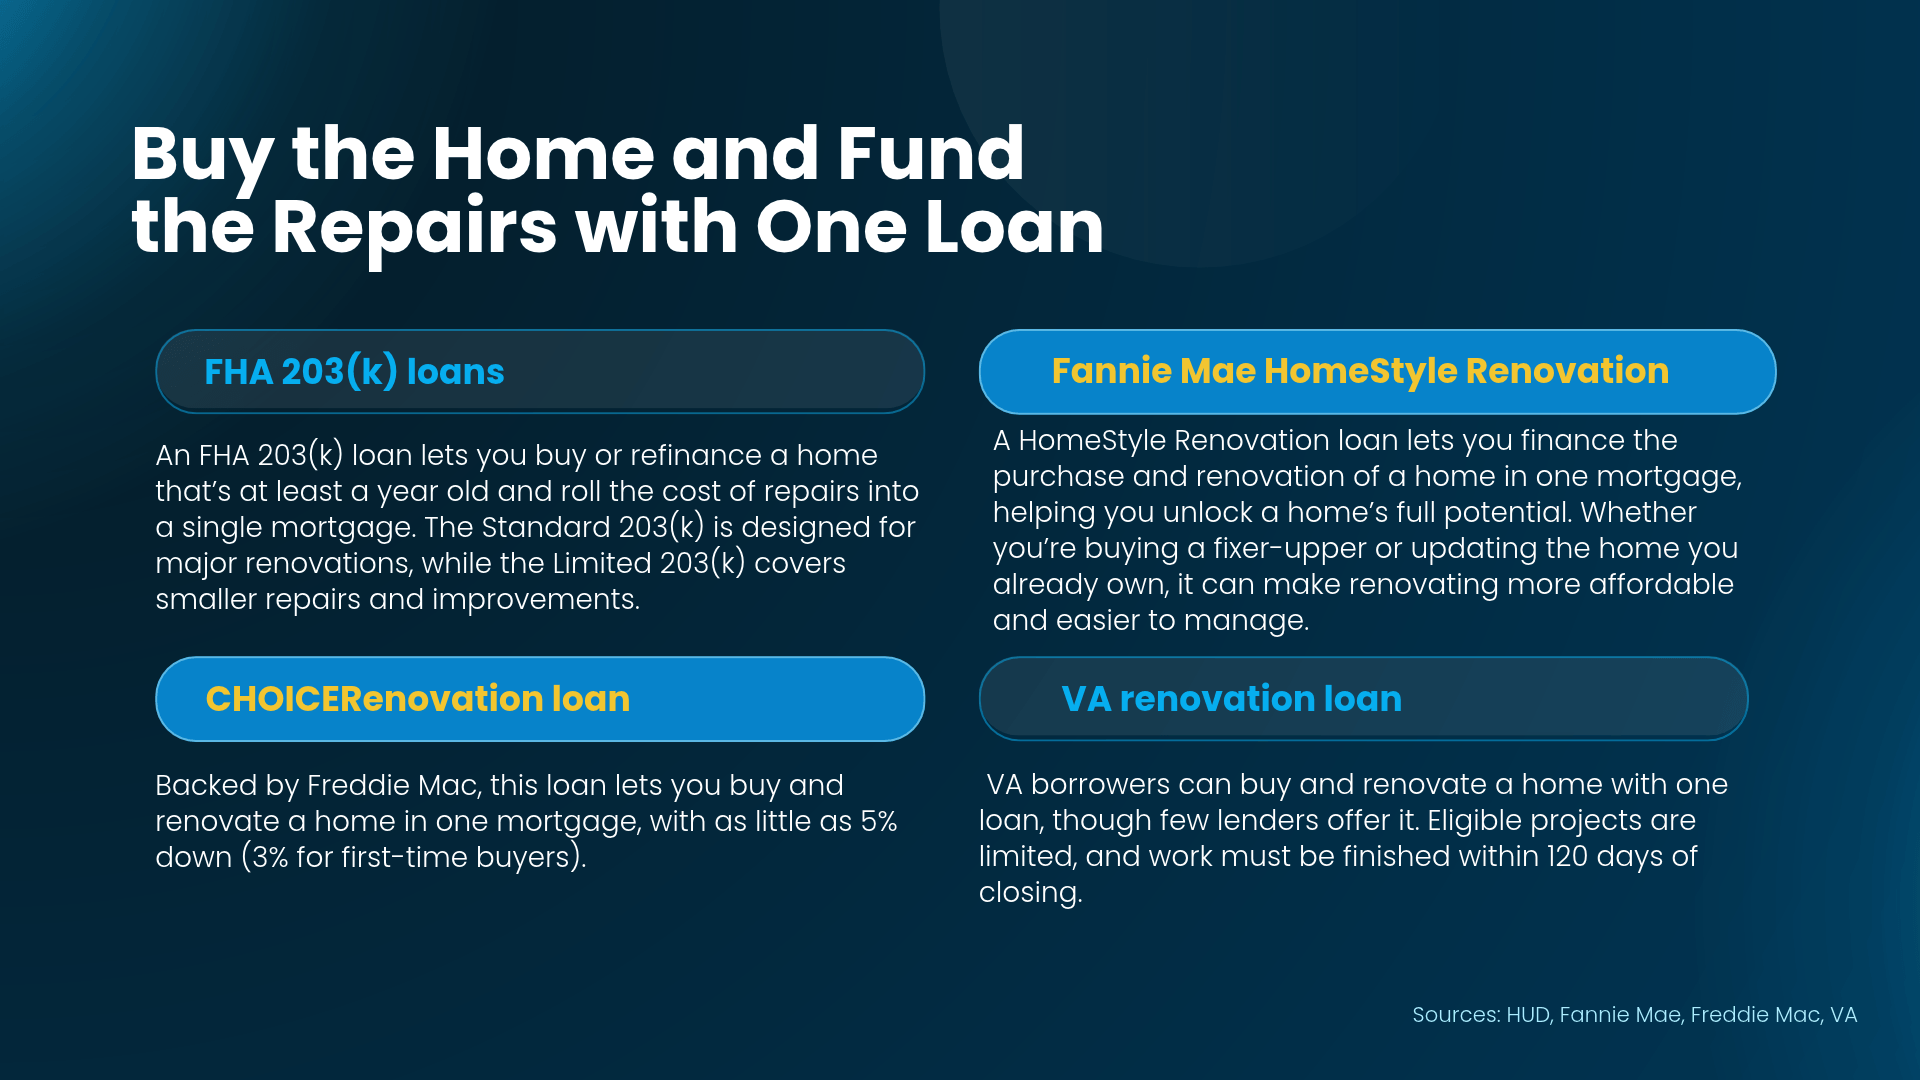
A renovation mortgage lets you fold the cost of the work into your home loan, so you aren’t paying for every project out of savings after closing. Here are four common programs (see visual below):
- FHA 203(k): Buy or refinance a home that’s at least a year old and include repair costs in one mortgage. The Standard 203(k) is built for major renovations; the Limited 203(k) covers smaller repairs and improvements.
- Fannie Mae HomeStyle Renovation: One mortgage covers both the purchase and the renovation, whether you’re buying a fixer-upper or updating a home you already own.
- Freddie Mac CHOICERenovation: Buy and renovate with a single loan and as little as 5% down, or 3% for first-time buyers.
- VA renovation loan: Eligible borrowers can buy and fix up a home with one loan, though few lenders offer it, eligible projects are limited, and the work has to be done within 120 days of closing.
Each program has its own guidelines, and not every lender handles all of them. Ask a lender you trust which ones they offer and which fits how you want to approach the work. If this would be your first home, look at these alongside the first-time home buyer programs in New Jersey.
Local Tax Incentives for Fixer-Upper Renovations
Some municipalities offer property tax breaks to owners who improve a home and raise its value. These programs differ from place to place, so confirm with the town or a tax professional before you count on one.
To look on your own, visit the official .gov site for the town or county you’re considering and search for terms like “home rehabilitation,” “property tax incentive” or “housing repair.” Our team can also help you find homes that need work in the Morris County neighborhoods on your list.
Fixer-Upper FAQs
How much cheaper is a fixer-upper than a move-in-ready home?
AmeriSave estimates fixer-uppers typically sell for 20% to 30% below market value. The real discount depends on the home’s condition and the local market, so get contractor estimates before deciding what to offer.
Can I include renovation costs in my mortgage?
Yes. Renovation loans such as FHA 203(k), Fannie Mae HomeStyle, Freddie Mac CHOICERenovation and VA renovation loans let you finance the purchase and the repairs together. Rules vary by program, and not every lender offers each one.
Is buying a fixer-upper in Morris County, NJ a good idea?
It can be if updated homes are outside your budget and you’re comfortable managing projects. With the single-family median at $773,000 in October 2026, a lower entry price can matter a lot. Plan for the inspection, permits and a realistic repair budget first.
Bottom Line
If updated homes keep landing above your budget, a house that needs some attention may be your way in. Set your repair budget and line up the right financing before you buy, then make the place your own over time as your budget allows.
This article is general information, not legal, tax, investment or financial advice. Market figures and forecasts can change. Talk with a qualified lender, tax professional or attorney about your situation.
Sources
- AmeriSave (fixer-upper pricing)
- National Association of Realtors (NAR), median existing-home price; Keeping Current Matters analysis
- Realtor.com (Danielle Hale)
- U.S. Department of Housing and Urban Development (FHA 203(k)), Fannie Mae, Freddie Mac, U.S. Department of Veterans Affairs
- NJ REALTORS / ShowingTime, Local Market Update, Morris County, October 2026
Adapted from Keeping Current Matters research.
Talk to the MorrisAgent Team
Want to see what this means for you? We’ll sit down and run the real numbers. Call (973) 200-4800, email [email protected], or stop by our office at 518 Main Street, Suite 102, Boonton. No pressure, and no surprises.